
Seven Chinese ministries published the country’s battery industry five-year plan on 28 September, and it is the first national plan written specifically for batteries rather than for vehicles or energy. Its targets are engineering numbers with dates attached: all-solid-state cells in early volume application by 2030, lithium cells rated at 15,000 cycles, and defect rates at leading manufacturers measured in parts per billion. The document also settles which chemistries are expected to coexist, and it lists robots as a battery market in their own right.
What the Battery Industry Five-Year Plan Actually Sets
The document is formally titled the New-Type Battery Industry Development 15th Five-Year Plan, issued as MIIT Joint Regulation [2026] No. 220 and published on 28 September by the Ministry of Industry and Information Technology together with the National Development and Reform Commission, the Ministry of Transport, the Ministry of Commerce, the State Administration for Market Regulation, the National Energy Administration and the National Railway Administration. The signing date is 14 September; the publication date is 28 September. It sits under China’s 15th Five-Year Plan, which covers 2026 to 2030.
Its definition of scope is worth noting, because the term it uses is broader than it looks. “New-type batteries” are defined as storage and conversion devices built around new mechanisms, materials, structures or processes, with lithium, sodium and flow batteries named as the representative types. Saying lithium is inside the definition matters: this plan is not a programme for exotic technologies on the fringe of a lithium industry. It is a plan for the whole industry, with the newer chemistries positioned inside it.
The headline targets for 2030 are three. All-solid-state batteries reach preliminary volume application. Long-life lithium cells reach 15,000 cycles. Leading manufacturers reach defect rates in the parts-per-billion range. Alongside those sits a set of qualitative goals about domestic supply chains, standards, recycling and exports, and the plan splits its work into five areas, 19 key tasks and five dedicated columns.
The baseline against which those targets should be read comes from the same ministry briefing: during the 14th Five-Year Plan period, China’s new-type battery industry passed RMB 1 trillion in total output value, mass-produced cells exceeded 300 Wh/kg in energy density, and the best cycle life achieved exceeded 12,000 cycles.
15,000 Cycles Is Longer Than the Plant It Sits In
That last comparison is where the plan gets interesting for anyone outside China.
Going from more than 12,000 cycles to 15,000 is a 25% improvement — but on the industry’s best recorded result, not on a typical cell, and not on a laboratory figure. Extend the target further and it becomes something else entirely. At one full discharge per day, 15,000 cycles is just over 41 years of operation. The best cells in service today, at 12,000 cycles, already reach 33 years on the same basis.
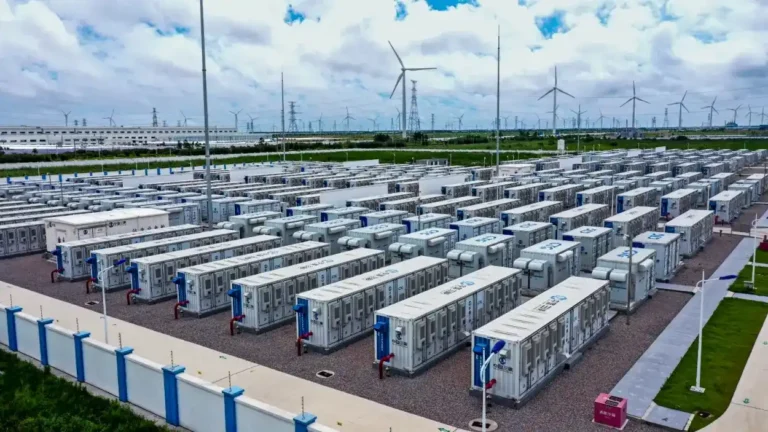
Grid-scale storage projects are typically engineered and financed on 20 to 25 year horizons, and battery augmentation is normally planned as a recurring cost, with packs replaced or topped up every seven to ten years. A cell that outlives the asset changes the shape of that model. It removes augmentation from the operating budget, and it moves the question of whether a storage project makes money away from the cell and onto whatever the market pays for the service — the price spread, the capacity payment, or the contracted grid service.
That is a real shift, and it is measurable. It is also why recent moves in this direction deserve attention: the storage cell price turn in China and the recent push on cycle life from cell makers are all pointing at the same objective, which is that the battery stops being the thing that wears out.
Solid-State by 2030, Without a Volume
“Preliminary volume application” is the phrase the plan uses for all-solid-state cells by 2030, and it is deliberately softer than a production target. There is no gigawatt-hour figure attached, no specification of vehicle or storage applications, and no allocation between the two.
That absence is the most informative part of the target, because the surrounding plan does commit to specifics elsewhere. It calls for accelerating the industrialisation technology for all-solid-state cells rather than only the research, for raising the volume-manufacturing capability of high-conductivity solid electrolytes, and — separately — for launching standards work covering all-solid-state and sodium batteries. Standards before volume is the conventional sequence, and it tells you the plan is treating solid state as a technology moving from pilot to manufacturing rather than one already there.
The rest of the market is on the same page. Mercedes-Benz began evaluating ProLogium’s Gen 4 cells last month while the supplier’s shipping product is an earlier generation, and Chinese automakers have demonstrated solid-state packs without committing to production volumes. Our coverage of the 2027 production race, BYD’s demonstration pack, FAW’s pilot line and Mercedes’ evaluation programme shows the same pattern everywhere: cells exist, lines exist, volume does not.
The Supply System Is Now Explicitly Multi-Chemistry
The plan states that China will build a supply system led by lithium batteries with sodium and flow batteries developing alongside them. That is a change of register from a decade in which policy attention and capital both flowed toward one chemistry.
What sits behind it is straightforward. Sodium cells trade energy density for cost and low-temperature performance, and they avoid lithium entirely; flow batteries trade power density for duration and cycle life. Both have spent years as pilot projects. A national plan that names them as part of the supply system rather than as research directions is a statement about where grid storage is expected to grow. The industry has been moving the same way — Hithium’s sodium-ion storage system and CATL’s sodium push into Europe are both recent examples.
Three other chemistry-specific lines are named. The plan calls for industrialising aqueous batteries and ultra-fast-charging batteries, and for improving the volume manufacturing of high-performance solid electrolytes. It also calls for flexible and shaped batteries for wearables, smart home devices and mobile medical equipment — a consumer-electronics line that sits outside the vehicle and grid story.
The Customer List Changed
The applications the plan expects batteries to electrify now include ships, aviation, industrial machinery, agricultural machinery and intelligent robots. Energy storage is listed across generation-side, grid-side, industrial park and data centre applications.
Robots and data centres are the two additions with the most commercial weight behind them. A humanoid robot carries roughly two kilowatt-hours and can carry a cell price that a car cannot, which is why solid-state cells are reaching robots before they reach vehicles. Data centre backup and load-shifting has become a distinct storage segment with its own engineering requirements. Both appeared in the last year’s news before they appeared in a plan, which makes them the parts of this document most likely to be quoted by equipment makers over the next twelve months.
What the Plan Does Not Say
Four gaps are worth keeping in mind before anyone treats this as a forecast.
The plan sets no capacity target. There is no gigawatt-hour number for 2030, no export volume, no share of global supply. The only quantitative production-adjacent targets are the cycle-life and defect-rate figures, both of which describe quality rather than scale.
It does not choose between technologies. The plan explicitly constructs a multi-chemistry supply system rather than picking a winner, which means it cannot be read as an endorsement of any single chemistry’s commercial prospects.
“Parts per billion” is not defined against a measurement method. A defect rate of one in a billion is only meaningful with the denominator stated — cells, packs or systems — and the plan does not state it.
And nothing here is binding on any company. This is an industrial plan, not a subsidy schedule or a mandate. Its financial content is limited to supporting financing access for qualifying supply-chain companies and coordinating existing funding channels.
The Bottom Line: China’s seven-ministry battery industry five-year plan, published on 28 September as MIIT Joint Regulation [2026] No. 220, sets three 2030 targets: preliminary volume application of all-solid-state cells, 15,000 cycles for long-life lithium cells, and parts-per-billion defect rates at leading manufacturers. The ministry’s own baseline is that the industry’s best cycle life already exceeds 12,000 cycles and mass-produced cells already exceed 300 Wh/kg, making the cycle-life goal a 25% improvement on the leading result — equivalent to over 41 years of daily cycling, longer than the storage plants the cells will sit in. The plan sets no capacity target, does not choose a chemistry, and names lithium, sodium and flow batteries as coexisting parts of one supply system.
Notes: All targets, baselines and task descriptions are taken from the plan and the Ministry of Industry and Information Technology’s own explanatory note, with the 14th Five-Year Plan baseline figures reported by the ministry’s news service; the 41-year and 33-year figures, the 25% improvement calculation and the contrast with storage asset lifetimes are our arithmetic on the stated numbers and stated cycle figures. The plan contains no capacity, revenue or production-volume targets. EVsays has not independently verified the ministry’s baseline figures and did not attend any briefing. See our editorial policy and correction policy.
Sources & Further Reading
- Ministry of Industry and Information Technology — “《新型电池产业发展”十五五”规划》解读” (explanation of the plan) — the 2030 targets in the ministry’s own words, the five areas and 19 tasks, and the application list covering vehicles, ships, aviation, robots, machinery and data centres.
- Xinhua (新华网) — “七部门联合印发《新型电池产业发展”十五五”规划》” (2026-09-28) — the issuing ministries, the regulation number 工信部联规〔2026〕220号, the publication date and the targets.
- China Industry and Information Technology News (中国工信新闻网, MIIT’s own news service) — “事关万亿级产业!七部门印发新型电池”十五五”规划” (2026-09-29) — the 14th Five-Year Plan baseline: RMB 1 trillion in output value, cells above 300 Wh/kg, and best achieved cycle life above 12,000 cycles, plus the recycled-battery and supply-system provisions.
- Guangming Daily (光明日报) — “《新型电池产业发展”十五五”规划》发布” (2026-09-29, page 10) — the standards work on all-solid-state and sodium batteries, the flexible and shaped battery applications, and the digital-technology provisions.
- EVsays — the technologies this plan covers: the 2027 solid-state production race, BYD’s solid-state demonstration, FAW’s pilot line, Mercedes-Benz evaluating ProLogium’s Gen 4, Hithium’s sodium-ion system, CATL’s sodium battery in Europe and storage cell pricing.